The short read
- U.S. duties on Canadian softwood lumber are cash deposits at rates Commerce resets every year; the rates in force on July 29, 2026 were 26.47% for West Fraser and 35.16% for most Canadian producers, with a 10% Section 232 tariff on top of both.
- West Fraser's hedge against the border is geography: 54% of its 6.5 billion board feet of lumber capacity is in the U.S. South, and the company says a majority of its U.S.-destination lumber sales now originate in U.S. mills.
- Housing starts of 1,427,000 at an annual rate in June 2026 are the demand side; the duty rate, OSB prices and the US$1,077 million on deposit are the swing factors, and the second quarter's US$59 million of adjusted EBITDA is not a normal year.
What the duty actually is
The United States has collected duties on Canadian softwood lumber since the Commerce Department published its current anti-dumping and countervailing duty orders on November 8, 2017 [2]. The word "duty" misleads an American reader, because very little of the money has been finally assessed. What an importer pays at the border is a cash deposit at whatever rate was in force on the day of entry; Commerce then reviews each calendar year's entries in a later administrative review, and the importer is refunded or billed the difference with interest [2].
The next rates are already visible. On April 14, 2026 Commerce published preliminary results of the seventh review, covering 2024 entries: a 4.77% dumping margin for West Fraser, 16.85% for Canfor and 10.66% for everyone else, and countervailing rates of 15.93% for West Fraser and 14.17% for the non-selected companies, with final results due within 120 days [3][4]. West Fraser said those rates would cut its combined deposit rate from 26.47% to 20.70% once finalized [8]; its July MD&A notes that Commerce amended the preliminary countervailing figure to 16.15% on June 29 [6].
A newer layer arrived in July. The 50% Section 338 tariffs that take effect on August 19, 2026 do not, by the company's reading, apply to its softwood lumber, OSB or about half of its MDF shipments; had they been in place this year they would have caught about 3% of its plywood and 20% of its LVL shipments to the United States [5]. That is the exposure as West Fraser describes it on July 29. The annexes that define it are the administration's to amend.
A producer with mills on both sides of the line
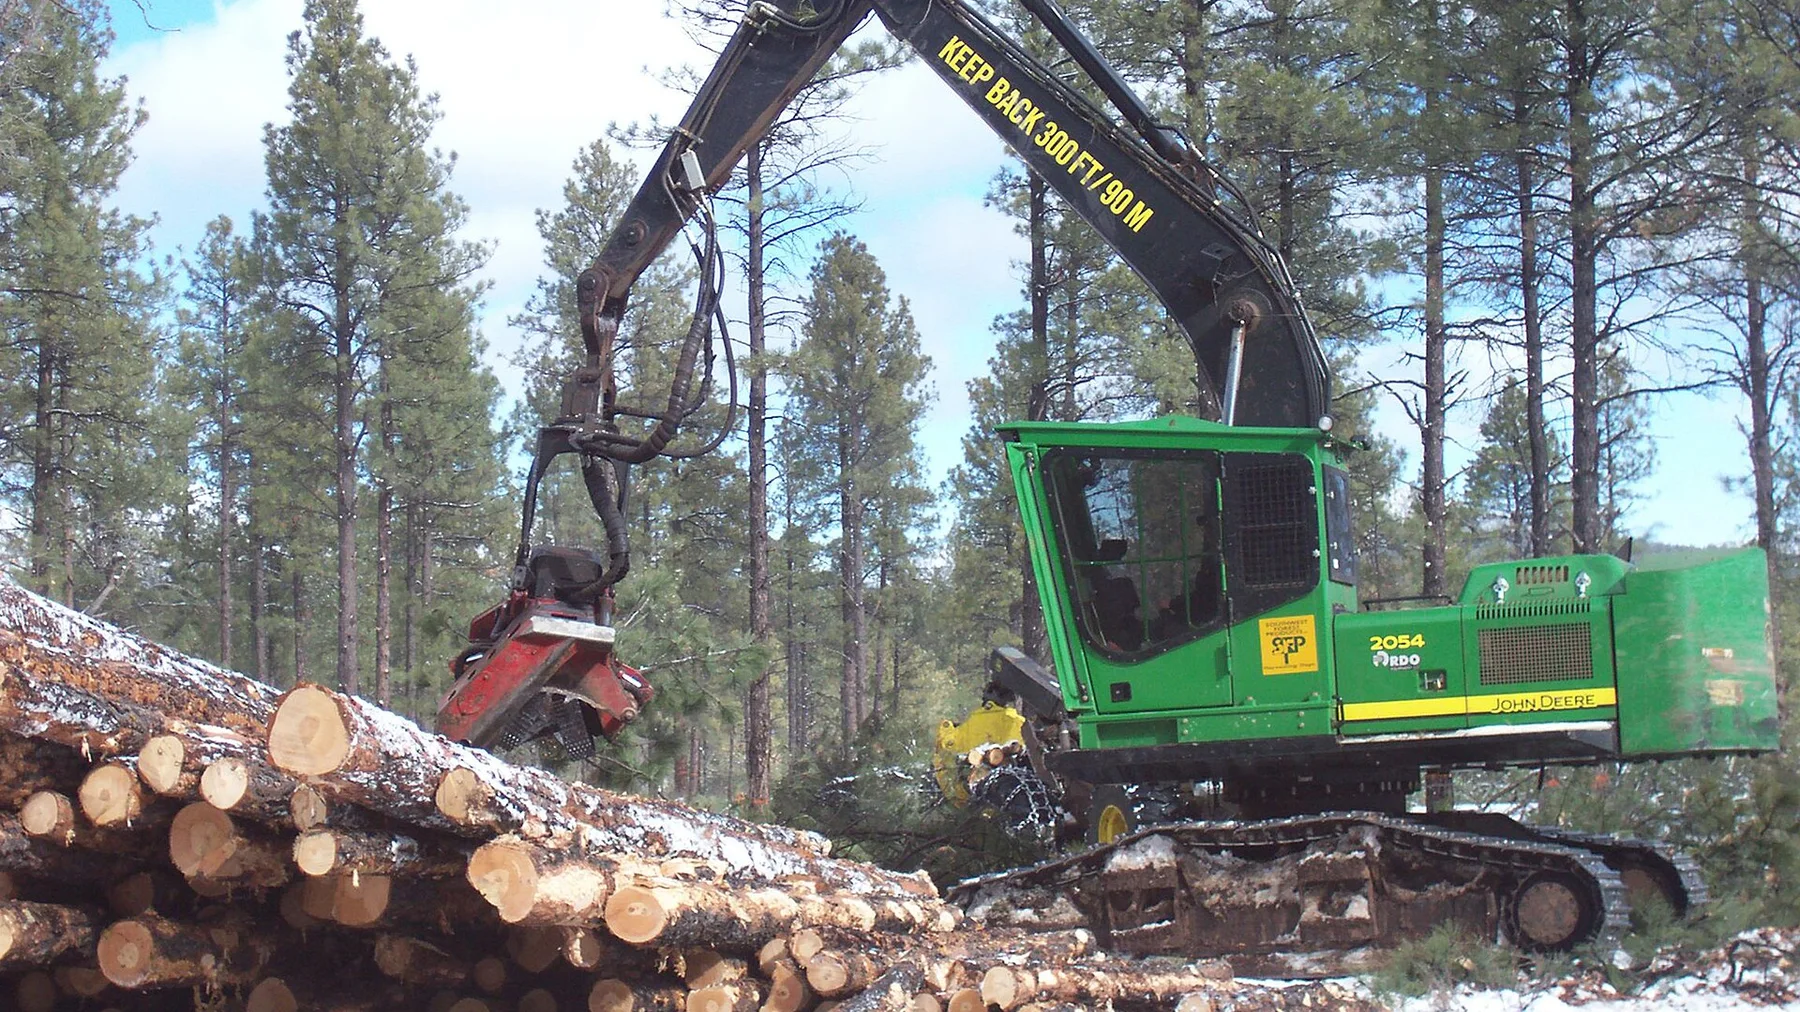
West Fraser's answer to the dispute has been to move the mills.
The second quarter extended the pattern. The new Henderson, Texas sawmill more than doubled its output between the first and second quarters; the 100 Mile House mill in British Columbia is permanently closed, as is the Augusta, Georgia mill shut in late 2025; and the High Level, Alberta OSB mill finished its wind-down in the quarter [5][6]. SPF shipments were 654 million board feet against 634 million of SYP, so the Canadian half still ships roughly as much as the American half [6].
What housing starts do to the price
Softwood lumber is a framing material, and single-family construction is its largest customer. The demand side of this piece is therefore a Census Bureau release.
West Fraser's own outlook, in the MD&A, names mortgage rates and affordability as the constraints on housing demand and reiterates its shipment targets rather than forecasting a price [6]. We would not do better.
The second quarter in numbers
For context, 2025 as a whole produced sales of US$5,462 million, a net loss of US$937 million and adjusted EBITDA of US$56 million, with the lumber segment at negative US$100 million including US$67 million of duty expense from the finalization of the sixth review; the OSB business earned US$153 million and kept the company's cash flow positive [14]. Neither 2025 nor the first half of 2026 is a normal year, and a reader who annualizes either will get the wrong answer.
Keep the valuation perimeter consistent
West Fraser reports in U.S. dollars and lists on the NYSE as well as the TSX, so the comparison with U.S. producers needs no currency step [5]. It does need a cycle step: any multiple on US$56 million of 2025 adjusted EBITDA is meaningless, and a multiple on the second quarter's US$59 million annualized is not much better. There were 76,022,344 Common and 2,281,478 Class B shares outstanding at July 28, 2026, no shares were repurchased in the first seven months of the year, and the quarterly dividend is US$0.32 [6][5]. The US$1,077 million on deposit belongs in the perimeter as a separate line: neither cash nor a sunk cost, but a claim whose value depends on Commerce.
What would change our view
The seventh review's final results are due within 120 days of April 14 [3]. A final combined rate for West Fraser at or below the 20.70% the company expects, published on schedule, would confirm that the deposit mechanism is working in its favor for 2024 entries; a rate above the preliminary one, or a delay into the autumn, would tell us to add another quarter of 26.47% deposits to the cash model [8][6]. A Section 338 annex that brought softwood lumber or OSB inside the 50% tariff would change the hedge arithmetic for every Canadian mill at once. On the demand side, a return of starts toward May's 1,199,000 rate would be the signal that the second quarter's price recovery was a weather pattern, not a season [11].
One business. Separate questions.
Company profiles
These companies have a documented connection to the theme. Inclusion is not a recommendation. Every figure is dated and sourced; blanks mean not yet verified.
West Fraser's head office is in Vancouver, and its shares trade on the Toronto Stock Exchange and the New York Stock Exchange under the same symbol,…
- Sales (latest quarter)
- US$1,434MQuarter ended Jul 3, 2026
- Net earnings (latest quarter)
- −US$61MQuarter ended Jul 3, 2026
- Adjusted EBITDA (latest quarter)
- US$59MQuarter ended Jul 3, 2026
All figures are in U.S. dollars, West Fraser's reporting currency. The second quarter of 2026 ended July 3, 2026; figures are from the July 29, 2026 news release, the interim MD&A and the interim financial statements filed on EDGAR the same day. Annual figures are from the February 11, 2026 release. Adjusted EBITDA is management's non-IFRS measure as the company defines it. Lumber volumes are in million board feet (MMfbm); OSB in million square feet on a 3/8-inch basis. Blank means not yet verified, never zero.
The other side of the thesis
What could break it
- The seventh review's final results, due within 120 days of April 14, 2026, could come in above the 20.70% combined rate West Fraser expects, or slip, and every month of delay is another month of deposits at 26.47%.
- The 10% Section 232 tariff on softwood lumber sits on top of any review outcome and is set by proclamation; the Section 338 annexes that currently leave lumber and OSB outside the 50% rate can be rewritten the same way.
- June's 1,427,000-unit starts rate followed a May figure of 1,199,000; a single month does not set a lumber price, and West Fraser's own outlook cites mortgage rates and affordability as the constraint on demand.
- OSB carried West Fraser in 2025 and earned US$13 million in the second quarter against US$68 million a year earlier on lower prices; panels can fall faster than lumber recovers.
- The U.S. South mills compete with American producers who post no deposits at all; the hedge removes the duty, not the price cycle.
- US$1,077 million on deposit is neither spendable cash nor a written-off cost; the US$436 million the company carries as a receivable is an estimate of what Commerce will eventually return, and the first quarter showed how a changed estimate becomes a US$114 million charge.
Read the original documents
Sources
-
1
Softwood lumber — recent developments
AR6 amended final rates (September 11, 2025): Canfor 35.47% AD + 12.12% CVD = 47.59%; West Fraser 9.65% + 16.82% = 26.47%; all others 20.53% + 14.63% = 35.16%; Section 232 10% on softwood timber and lumber from October 14, 2025; December 31, 2025 proclamation delaying increases on furniture, cabinets and vanities to January 1, 2027; Canada's CUSMA Chapter 10 challenges filed September 11, 2025; AR7 respondent selection April 2025.
-
2
Softwood lumber — frequently asked questions
Final determinations published November 8, 2017; annual administrative reviews set updated deposit rates and final assessment rates; importers post cash deposits at the rates in effect at entry and receive refunds or bills with interest after final results; CUSMA Chapter 10 panels and WTO review.
-
3
Certain Softwood Lumber From Canada: Preliminary Results and Intent To Rescind, in Part, of Antidumping Duty Administrative Review; 2024
Period of review January 1–December 31, 2024; preliminary dumping margins Canfor 16.85%, Resolute 13.25%, West Fraser 4.77%, non-examined companies 10.66%; final results within 120 days; all-others cash deposit rate 6.04%; case A-122-857.
-
4
Certain Softwood Lumber Products From Canada: Preliminary Results and Partial Rescission of Countervailing Duty Administrative Review; 2024
Preliminary subsidy rates Resolute 11.70%, West Fraser 15.93%, non-selected companies 14.17%; final results within 120 days; case C-122-858.
-
5
West Fraser Announces Second Quarter 2026 Results
Q2 2026 sales US$1.434B; net loss US$(61)M, US$(0.78)/share; adjusted EBITDA US$59M (Lumber US$41M, NA EWP US$13M, Europe EWP US$13M); Q1 2026 sales US$1.334B, net loss US$(188)M, adjusted EBITDA US$(66)M; cash US$74M; H1 capex US$159M; 2026 capex US$300–350M; dividend US$0.32; no buybacks January 1–July 28, 2026; shipment targets 2.4–2.7 Bfbm for SPF and SYP, NA OSB 5.9–6.3 Bsf; Henderson, Texas output more than doubled from Q1; High Level, Alberta OSB wind-down completed; Section 232 10% from October 14, 2025; Section 338 50% from August 19, 2026, with softwood lumber, OSB and about half of MDF not affected and about 3% of plywood and 20% of LVL U.S. shipments affected year-to-date; June starts 1.43M, permits 1.37M; TSX and NYSE: WFG; Vancouver.
-
6
Management's Discussion and Analysis, second quarter 2026 (Form 6-K, Exhibit 99.2)
Cash deposit rates ADD 9.65%, CVD 16.82%, combined 26.47%; AR7 preliminary CVD amended June 29, 2026 to 16.15% from 15.93%, ADD 4.77%; Q2 export duties, net, and tariffs US$45M (Q2 2025 US$21M); US$13M favorable adjustment; Lumber adjusted EBITDA US$41M / US$(84)M / US$15M for Q2-26 / Q1-26 / Q2-25; SPF shipments 654 / 555 / 696 MMfbm; SYP 634 / 604 / 680; OSB shipments 1,619 / 1,544 / 1,710 MMsf; NA EWP adjusted EBITDA US$13M / US$11M / US$68M; Q2 2025 sales US$1,532M, net loss US$(24)M, adjusted EBITDA US$84M; H1 2026 sales US$2,767M, net loss US$(249)M, adjusted EBITDA US$(7)M; cash from operations Q2 US$192M; capex Q2 US$65M; 76,022,344 Common and 2,281,478 Class B shares at July 28, 2026; net debt US$317M, 5% of capital; outlook citing mortgage rates and affordability; 100 Mile House closure; Blue Ridge restart.
-
7
Condensed consolidated interim financial statements, second quarter 2026 (Form 6-K, Exhibit 99.1)
Export duties paid and payable on deposit with the USDOC US$1,077M at July 3, 2026 and US$1,003M at December 31, 2025; export duties receivable US$436M; export duties payable US$290M; US$15M of AR1 anti-dumping liquidation payments received in Q2 2026; shareholders' equity US$5,566M.
-
8
Notice of First Quarter Results Conference Call and Softwood Lumber Duties and Operational Update
AR7 preliminary rates would reduce the combined cash deposit rate from 26.47% to 20.70%; US$73M non-cash charge reflecting previously recorded CVD estimates of 2.19% and 6.85% against the 15.93% preliminary rate, plus US$41M for a change in the estimate of recoverable amounts; US$15M AR1 refund expected; rates expected to be finalized and take effect later in 2026.
-
9
West Fraser Announces First Quarter 2026 Results
Q1 2026 Lumber adjusted EBITDA US$(84)M including a US$114M charge for duty adjustments related to prior periods; net loss US$188M; High Level wind-down; Blue Ridge back to normal rates after the January fire.
-
10
Investor Presentation, April 2026 (Q1 2026)
Slide 13: lumber capacity at December 31, 2025 of 6.5 Bfbm across 28 facilities (SPF 3.0, SYP 3.5). Slide 17: U.S. South 54%, Alberta 28%, British Columbia 18%, against 11% U.S. South and 89% Canada in 2004. Slide 37: cash on deposit US$1,035M at Q1 2026; a majority of U.S.-destination lumber sales from U.S. origins. The slide's duty-rate table could not be read reliably and is not used.
-
11
Monthly New Residential Construction, June 2026
Privately owned housing starts 1,427,000 SAAR in June 2026, 19.0% above the revised May rate of 1,199,000 and 3.5% above June 2025 (1,379,000); single-family starts 895,000; permits 1,367,000, down 3.0% from May and 2.3% from a year earlier; single-family permits 871,000; completions 1,392,000.
-
12
Softwood Lumber Subsidies Report to the Congress
Covers July 1–December 31, 2025; Canada 82.15% of U.S. softwood lumber imports, Germany 6.43%, Sweden 3.87%; AR7 preliminary results issued April 14, 2026.
-
13
Amendments to Adjusting Imports of Timber, Lumber, and Their Derivative Products Into the United States (Proclamation 11000)
10% ad valorem on softwood timber and lumber; 25% on upholstered wooden products, kitchen cabinets and vanities, with increases to 30% and 50% delayed to January 1, 2027.
-
14
West Fraser Announces Fourth Quarter 2025 Results
FY2025 sales US$5.462B; net loss US$(937)M, US$(12.08)/share; adjusted EBITDA US$56M, Lumber US$(100)M including US$67M of duty expense from the finalization of AR6, NA EWP US$153M; cash US$202M at December 31, 2025; 2026 shipment guidance 2.4–2.7 Bfbm each for SPF and SYP.
-
15
Certain Softwood Lumber Products From Canada: Amended Final Results of Antidumping Duty Administrative Review; 2023
Canfor 35.47%; companies not selected 20.53%; West Fraser's 9.65% unchanged from the original final results; all-others cash deposit rate 6.04%.
-
16
Commerce Department Announces Final Results of Softwood Lumber from Canada Countervailing Duty Administrative Review
Sixth review (2023 entries): subsidy rates from 12.12% to 16.82%; non-selected companies 14.63%, up from 6.74% in the previous review.