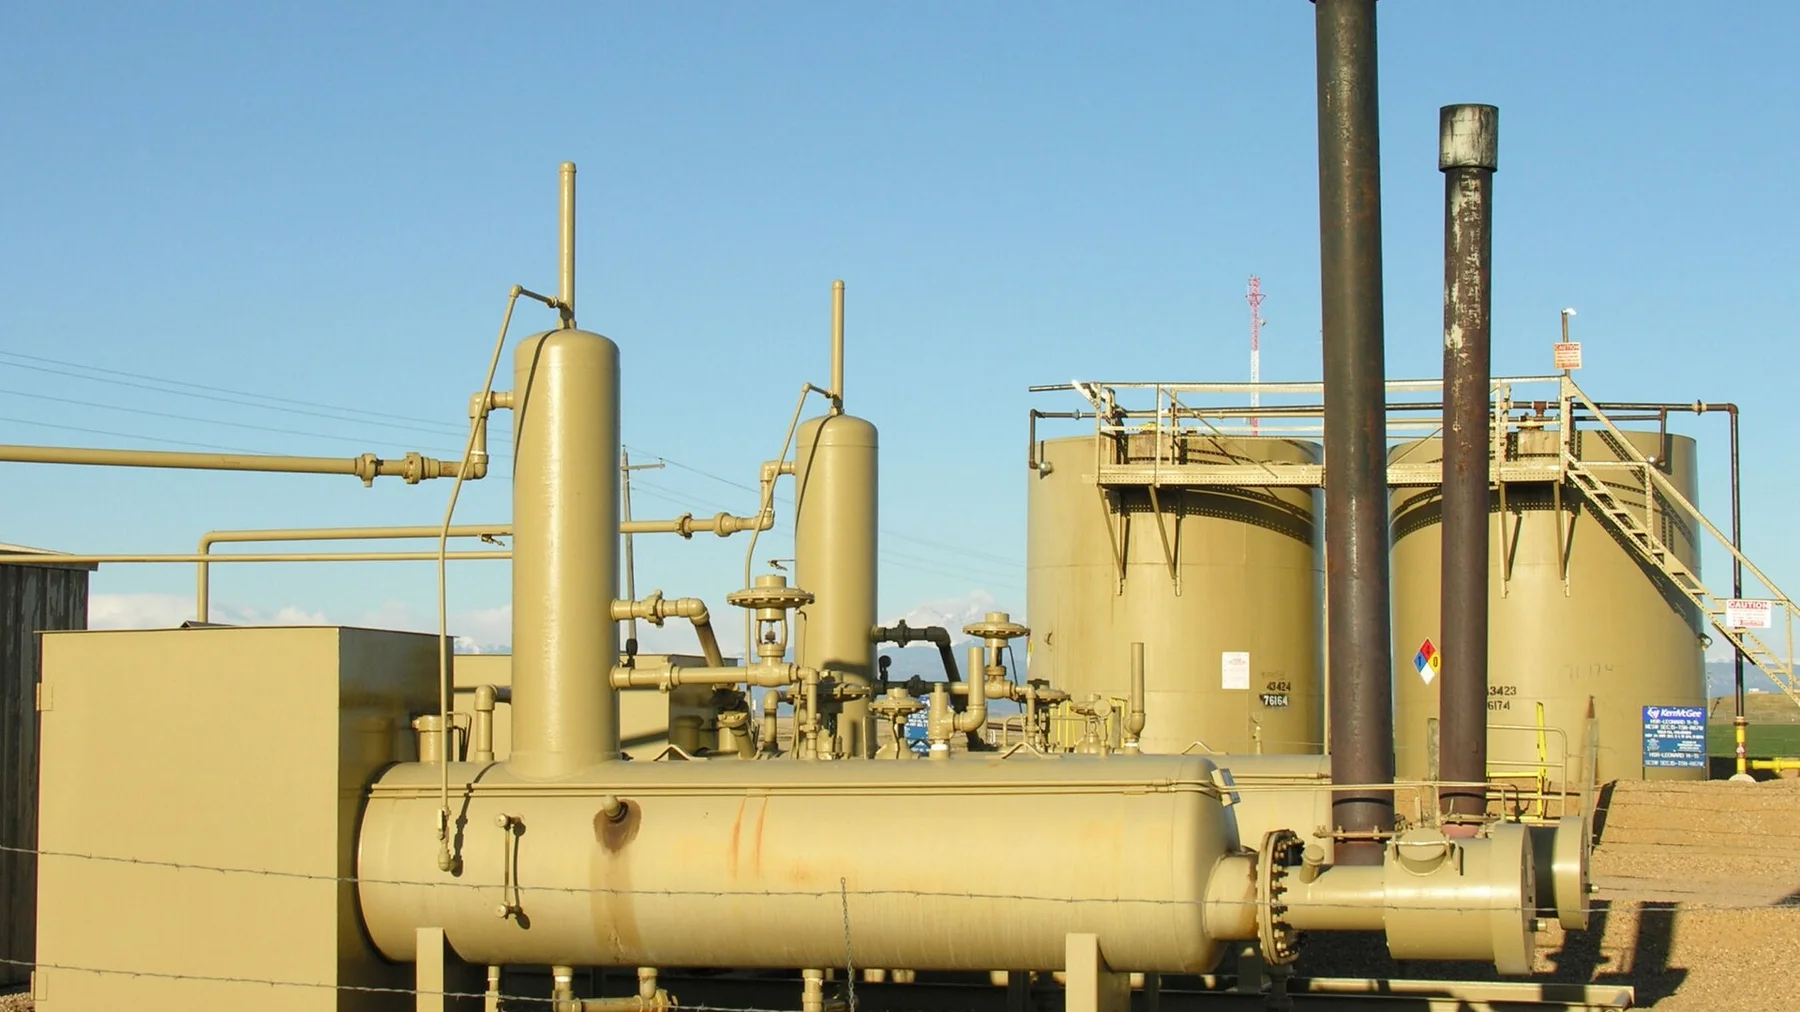
Natural gas and liquids (Montney, Alberta Deep Basin) / Operating producer / Oil & Gas
Tourmaline Oil
TSXTOUOTCTRMLF
Tourmaline calls itself Canada's largest and most active natural gas producer, and its stated aim is to produce the lowest-development-cost gas in North America [1]. The head office is in Calgary [1]. The shares trade on the Toronto Stock Exchange as TOU [1]; there is no NYSE or Nasdaq listing, but the stock is quoted over the counter in U.S. dollars under the symbol TRMLF, which most U.S. brokers can trade [2]. The company reports in Canadian dollars, and its natural gas prices are quoted per thousand cubic feet (mcf).
Production averaged 594,198 boe/d in the quarter ended June 30, 2026, of which 2,886,412 mcf/d was natural gas and 113,129 bbl/d was crude oil, condensate and natural gas liquids [1]. That was below the 638,196 boe/d averaged in 2025 because, as the company put it, it injected additional gas into storage and deferred activity in response to low second-quarter prices; the AECO 5A benchmark averaged C$1.66/mcf in the quarter [1][3]. Full-year 2026 guidance is 620,000–640,000 boe/d with a year-end exit rate of 660,000 boe/d including storage withdrawals [1]. The reserve base at December 31, 2025 was 6,091,751 Mboe proved plus probable and 3,255,943 Mboe proved, after 829 million boe of 2P additions in the year [3]. The two core areas named in the results are the northeast British Columbia Montney, where first-half 2026 wells came in 28% above the five-year average on 90-day rates, and the Alberta Deep Basin, 14% above [1].
The business case rests on selling gas somewhere other than Alberta. Tourmaline realized C$3.12/mcf in the second quarter against the C$1.66 AECO benchmark, a C$1.46 premium, through a mix of hedges, export-market sales and storage [1]. It has 220,000 MMBtu/d exposed to Asian and European LNG prices (JKM and TTF) in 2026, rising to 253,000 MMBtu/d by the end of 2027 and 333,000 MMBtu/d by the end of 2028; for the rest of 2026, 100 MMcf/d was hedged at C$16.25/mcf in international markets and 164 MMcf/d at C$6.32/mcf in the western United States, within 1,014 MMcf/d of total hedges at C$4.97 [1]. It holds storage at Dimsdale in Alberta, Dawn in Ontario and Wild Goose in California, and in July 2026 signed an LPG marketing agreement with AltaGas that routes propane and butane by unit train from its Groundbirch-Monias plant to the Ridley Island terminals on the B.C. coast [1]. For the U.S. reader, the backdrop is that the United States imported an average of 8.6 Bcf/d of natural gas from Canada in 2025, 1% more than in 2024, and the value of those imports rose 52% [4].
Second-quarter 2026 cash flow (management's non-GAAP measure) was C$786.1 million against C$822.8 million a year earlier, net earnings were C$184.4 million against C$514.6 million, capital spending was C$554.8 million and free cash flow was C$192.1 million [1]. Operating costs were C$4.59/boe and transportation C$5.21/boe, for an operating netback of C$15.14/boe [1]. Net debt was C$1.508 billion at June 30, 2026, which the company puts at 0.4 times forecast cash flow against a long-term target of C$1.75 billion [1]. For 2025 as a whole, cash flow was C$3,395.6 million, net earnings C$262.7 million and capital spending C$2,932.3 million, with net debt of C$1,523.9 million at year end [3]. The 2026 capital budget is C$2.55 billion, cut by C$350 million in March, and the company estimated 2026 free cash flow at C$880 million on the strip at the time of its July 29 release (NYMEX US$3.54/MMBtu, AECO C$1.90/mcf, WTI US$81.06) [1][3].
Capital returns changed shape in the third quarter. On September 22, 2026 Tourmaline agreed to sell 10,000,000 shares of Topaz Energy, the royalty company to which it had sold a gross overriding royalty for C$38.7 million in the second quarter, at C$28.75 for gross proceeds of about C$287.5 million, cutting its stake from 19,931,097 shares (12.9%) to 9,931,097 (6.4%), and said it would use the proceeds to buy back its own shares under a normal course issuer bid renewed in August for up to 15,544,068 shares, 4% of the 388,601,707 outstanding at July 31, 2026 [5][6]. The quarterly base dividend rises 5% to C$0.525 (C$2.10 annualized) from the fourth quarter of 2026, after C$0.50 was paid on September 29 [5][7]. Growth is deliberately paused: the first phase of the northeast B.C. Montney build-out (Aitken plant expansion in the fourth quarter of 2026, Groundbirch-Monias deep-cut plant in the fourth quarter of 2027, adding about 1.1 Bcf/d of gas and 50,000 bbl/d of liquids) will be followed by a one-year gap before Phase 2 unless gas prices improve on a sustained basis [1]. The chief financial officer, in the role since 2008, retires on November 1, 2026; a successor has been named [1].
Primary assets & business
- Northeast British Columbia Montney (core area; first-half 2026 wells 28% above the five-year average on IP90; Phase 1 infrastructure: five of six regional connector pipelines complete, Aitken plant expansion Q4 2026, Groundbirch-Monias deep-cut plant Q4 2027, together about +1.1 Bcf/d gas and +50,000 bbl/d liquids) [1]
- Alberta Deep Basin (core area; first-half 2026 wells 14% above the five-year average on IP90) [1]
- South Montney: Aduro Resources acquired in Q2 2026 for about C$100 million (C$50 million cash plus 1.5 million Topaz shares), adding 174 net Tier 1 Montney locations [1]
- Natural gas storage at Dimsdale (Alberta), Dawn (Ontario) and Wild Goose (California); Q2 2026 injections 8,867 boe/d, withdrawals expected Q4 2026–Q1 2027 [1]
- Export marketing: 220,000 MMBtu/d exposed to JKM/TTF pricing in 2026 (333,000 MMBtu/d by exit 2028); western U.S. and international hedges; LPG marketing agreement with AltaGas via the REEF and RIPET terminals at Ridley Island with a unit-train loading facility under construction at Groundbirch-Monias [1]
- Topaz Energy Corp. equity: 9,931,097 shares (6.4%) after the October 2026 secondary offering closes, down from 19,931,097 (12.9%) [5]
- Reserves at Dec 31, 2025: 6,091,751 Mboe proved plus probable; 3,255,943 Mboe proved [3]
Financial position
| Production (latest quarter) | 594,198 boe/dNatural gas 2,886,412 mcf/d; oil, condensate and NGLs 113,129 bbl/d. 2026 guidance 620,000–640,000 boe/d; exit 660,000 boe/d. | Quarter ended Jun 30, 2026 [1] |
|---|---|---|
| Production (fiscal 2025) | 638,196 boe/dNatural gas 2,946,447 mcf/d; liquids 147,121 bbl/d. | Year ended Dec 31, 2025 [3] |
| Cash flow (latest quarter) | C$786.1MManagement's non-GAAP measure; C$2.02 per diluted share. Q2 2025: C$822.8M. First half 2026: C$1,648.2M. | Quarter ended Jun 30, 2026 [1] |
| Free cash flow (latest quarter) | C$192.1MCash flow less capital expenditures of C$554.8M, excluding acquisitions and dispositions. First half 2026: C$394.1M. 2026 estimate C$880M at the strip quoted on July 29, 2026. | Quarter ended Jun 30, 2026 [1] |
| Net earnings (latest quarter) | C$184.4MC$0.47 per diluted share. Q2 2025: C$514.6M. | Quarter ended Jun 30, 2026 [1] |
| Cash flow (fiscal 2025) | C$3,395.6MC$8.84 per diluted share. Net earnings C$262.7M; capital expenditures C$2,932.3M. | Year ended Dec 31, 2025 [3] |
| Realized natural gas price | C$3.12/mcfAECO 5A benchmark C$1.66/mcf; realized liquids price C$65.55/bbl. | Quarter ended Jun 30, 2026 [1] |
| Operating netback | C$15.14/boeOperating costs C$4.59/boe; transportation C$5.21/boe; cash G&A C$0.87/boe. | Quarter ended Jun 30, 2026 [1] |
| Net debt | C$1,508M0.4x forecast cash flow by the company's measure; long-term target C$1.75B. Dec 31, 2025: C$1,523.9M [3]. | Jun 30, 2026 [1] |
| Proved plus probable reserves | 6,091,751 MboeProved 3,255,943 Mboe; 829 million boe of 2P additions in 2025. | Dec 31, 2025 [3] |
| 2026 capital budget | C$2.55BReduced by C$350M in March 2026 [3]; 2027 C$2.55B; 2028 C$2.3B. | Jul 29, 2026 [1] |
| Market capitalization | Not yet verifiedNot verified against a dated close. |
Figures are in Canadian dollars unless marked US$. Quarterly figures are for the three months ended June 30, 2026 from the July 29, 2026 news release; annual figures are from the March 4, 2026 year-end release. Cash flow, free cash flow and operating netback are management's non-GAAP measures as the company defines them. Reserves are company-reported figures from its independent evaluation at December 31, 2025. Blank means not yet verified, never zero.
Ownership & capital structure
| Common shares outstanding | 388,601,707Diluted weighted average for Q2 2026: 389,669,745 [1]. | Jul 31, 2026 [6] |
|---|---|---|
| Normal course issuer bid | Up to 15,544,068 shares4% of shares outstanding. No shares were bought under the prior bid; the September 2026 Topaz sale proceeds are earmarked for repurchases [5]. | Aug 10, 2026 – Aug 9, 2027 [6] |
| Base dividend | C$0.50 per share quarterly, rising to C$0.525C$0.50 paid September 29, 2026 (record September 15) [1][7]; C$0.525 (C$2.10 annualized) from Q4 2026, payable December 31, 2026. Eligible dividend for Canadian tax; Canadian withholding tax applies to U.S. holders outside qualified retirement accounts. | Sep 22, 2026 [5] |
| Topaz Energy stake | 19,931,097 shares (12.9%) before the offering9,931,097 shares (6.4%) after the 10,000,000-share sale at C$28.75; 5.4% if the 15% over-allotment is exercised. Closing expected on or about October 8, 2026. | Sep 22, 2026 [5] |
| Significant shareholders | Not yet verifiedNot verified; see the proxy circular on SEDAR+. |
What has to happen next
- Closing of the Topaz secondary offering on or about October 8, 2026 and the pace of buybacks under the 15,544,068-share NCIB afterward [5][6].
- First C$0.525 quarterly dividend, expected to be declared in early December and paid December 31, 2026 [5].
- Aitken plant expansion start-up in the fourth quarter of 2026; storage withdrawals through the fourth quarter of 2026 and first quarter of 2027 toward the 660,000 boe/d exit rate [1].
- Groundbirch-Monias deep-cut plant and the adjacent LPG rail loading facility in the fourth quarter of 2027 [1].
- Chief financial officer transition on November 1, 2026; successor named [1].
- Whether Phase 2 of the northeast B.C. build-out proceeds on the original schedule depends, in management's words, on natural gas prices improving on a sustained basis [1].
- Third-quarter 2026 results and any update to the 2026 free cash flow estimate of C$880 million [1].
Research checkpoints, not a dated event calendar or a promise of outcomes.
Valuation context
We publish no valuation conclusion. The relevant comparison for Tourmaline is not an AECO multiple but the realized price it achieves above AECO, which was C$1.46/mcf in the second quarter of 2026, and the share of volumes exposed to international LNG pricing, which the company expects to grow through 2028 [1]. A dated comparison with U.S. gas producers would need the same price deck for Henry Hub, AECO and JKM, the 388,601,707-share count, net debt of C$1.508 billion at June 30, 2026, and the Topaz stake at a dated price after the October sale [6][1][5]. The company's own 2026 free cash flow estimate of C$880 million rests on the July strip and on its capital budget, both of which can move [1].
Mandatory reading
Key risks
- AECO was C$1.66/mcf in the second quarter of 2026 and the company cut activity and injected gas into storage in response; the realized premium depends on hedges and export capacity that roll over time [1].
- The international exposure is to JKM and TTF, prices set by Asian and European buyers; the hedge at C$16.25/mcf covers 100 MMcf/d for the rest of 2026, not the whole book [1].
- Phase 2 growth is on hold; if the Aitken or Groundbirch-Monias start-ups slip, the 660,000 boe/d exit rate and the free cash flow step-up in late 2027 and 2028 slip with them [1].
- Selling Topaz shares to fund buybacks converts a royalty income stream into a lower share count; whether that is value-accretive depends on the price paid for Tourmaline stock, which the company has not disclosed in advance [5].
- There is no U.S. exchange listing; the OTC quote under TRMLF can be thinner than the TSX line, and the dividend is paid in Canadian dollars less withholding tax [2].
- The United States is both the main export market for Canadian gas and a competing LNG exporter; a change in cross-border trade terms would affect the western U.S. hedges and pipeline flows the company relies on [4].
Source documents
-
1
Tourmaline Announces Strong Second Quarter Results and Liquids Marketing Agreement
Q2 2026: production 594,198 boe/d (gas 2,886,412 mcf/d; liquids 113,129 bbl/d); cash flow C$786.1M (Q2 2025 C$822.8M); net earnings C$184.4M (C$514.6M); capex C$554.8M; FCF C$192.1M; net debt C$1.508B; realized gas C$3.12/mcf vs AECO 5A C$1.66; liquids C$65.55/bbl; hedges; JKM/TTF exposure 220,000/253,000/333,000 MMBtu/d; AltaGas LPG agreement; storage; NEBC Phase 1; Aduro acquisition; Topaz royalty sale C$38.7M; 2026 guidance 620,000–640,000 boe/d, exit 660,000; capex C$2.55B; FCF estimate C$880M and strip; opex C$4.59/boe; transport C$5.21; netback C$15.14; dividend C$0.50 payable Sept 29; CFO transition; 'Canada's largest and most active natural gas producer'; Calgary head office; TSX: TOU.
-
2
Tourmaline Oil Corp. (TRMLF)
Confirms the OTC Markets quotation under TRMLF in U.S. dollars, with the primary listing on the TSX as TOU. Used for the symbol only; no price taken.
-
3
Tourmaline Achieves Record Production, Adds 829 Million BOE of 2P Reserves and Reduces 2026 EP Capex
FY2025: production 638,196 boe/d (gas 2,946,447 mcf/d; liquids 147,121 bbl/d); cash flow C$3,395.570M (C$8.84/diluted share); net earnings C$262.672M; capex C$2,932.280M; net debt C$1,523.871M; 2P 6,091,751 Mboe, 1P 3,255,943 Mboe, 829 MMboe added; 2026 EP capex C$2,550M (−C$350M); 2026 guidance 620,000–640,000 boe/d; 213,000 MMBtu/d JKM/TTF exposure in 2026.
-
4
The U.S.-Canada natural gas and electricity trade value rose in 2025
U.S. natural gas imports from Canada averaged 8.6 Bcf/d in 2025, 1% more than 2024, with value up 52%; U.S. exports to Canada 2.8 Bcf/d, US$2.6 billion.
-
5
Tourmaline and Topaz Announce $287.5 Million Bought Deal Secondary Offering of Topaz Common Shares and Tourmaline Announces Planned Share Repurchases and Base Dividend Increase
10,000,000 Topaz shares at C$28.75 for about C$287.5M; 15% over-allotment; Tourmaline's stake 19,931,097 (12.9%) to 9,931,097 (6.4%), 5.4% if exercised; closing about October 8, 2026; proceeds to NCIB repurchases; base dividend to C$0.525 (C$2.10 annualized), +5%, from Q4 2026.
-
6
Tourmaline Announces Renewal of Normal Course Issuer Bid
Up to 15,544,068 shares, 4% of 388,601,707 outstanding at July 31, 2026; term August 10, 2026 to August 9, 2027; no shares bought under the prior bid of up to 19,342,343.
-
7
Investors
TSX: TOU; quarterly base dividend of C$0.50 declared September 1, 2026, designated an eligible dividend; links to the Q2 2026 interim report.